Info
No 20% down payment for a home? 6 options many buyers don’t know about
Many people’s plans to buy a home stall on one question: where to get the 20% down payment? Six options many buyers do not know about.
As property owners or landlords, we usually think about yield, low heating costs or good tenants. But life sometimes has scenarios in store that none of us is truly prepared for, and home insurance becomes more important than ever. For me, that moment came on the day I got the call no owner ever wants to get: a fire had broken out in my house in Pärnu.
A fire is something we usually only see in the news or in films. But when flames and firefighting water destroy your own property, theory turns into painful reality within minutes. As a property owner you know the home must be insured, but until a real claim you may not think through what your home insurance actually covers and what happens when your home becomes uninhabitable overnight. I, however, was prepared, and this is what saved me from a huge financial blow and months of headaches: correctly chosen home insurance.
The moments after a fire are emotionally extremely hard. When the smoke clears, the question is no longer how much the insurance costs per year. Now you face the questions: What happens next? How do I rebuild the house? Who covers the damage? What about the rental income?
Fortunately, in all my dealings with property I have always kept one rule: no compromises on insurance terms. My house is insured with Salva Kindlustus, and this experience showed me in no uncertain terms what a professional partnership means in a moment of crisis.
The Salva team’s response was prompt and humane:
This real-life lesson confirmed one important truth to me as a property expert: home insurance is not just a cost item or a bank requirement, it is the safety guarantee for your business and your life’s work. This is not a sponsored collaboration; I simply know from personal experience that the topic matters and may help others too!
In the property market I see owners every day who go for the cheapest offer when choosing a policy. The house or apartment gets insured on paper, but nobody looks into the actual covers until an accident happens.
If you have rented out an apartment or own several properties, your home insurance must include specific additional covers:
Home liability insurance is aimed mainly at private individuals who, in the course of normal activities, cause damage in connection with owning their apartment, terraced house, house or other residence. Liability insurance covers damage caused to third parties, saving you tens of thousands of euros.
For the owner of a rental property, another important problem arises. If the rented apartment or house becomes uninhabitable after a fire or other major damage, it is not only the use of the property that is lost. The monthly rental income can disappear at the same time. If restoration takes several months, the lost amount can already be significant.
My insurance contract also included loss of rental income cover. It is one of those covers you may not think about at all when first renting out a property. Usually the focus is on insuring the house or apartment itself. In reality, a rental property is an investment, and a key part of that investment is regular cash flow.
With a rented property, a fire naturally affects the tenant too. If the house or apartment becomes uninhabitable, the person has to find a new place to live, at least temporarily. This is also a question the landlord should think about when choosing insurance.
The insurance market offers replacement housing covers. Salva, for example, describes in its home insurance materials the option of adding cover for the rental cost of replacement housing if the home becomes uninhabitable as a result of an insured event. Here it is important to look at the terms of the specific contract: who is insured, which costs are reimbursed, how long the cover lasts and what the compensation limits are.
If, after my experience, I had to give one recommendation to rental property owners, it would be simple: don’t choose insurance on price alone. The cheapest annual premium can seem like a good choice until something happens.
Before taking out insurance, ask at least:
Not every property owner necessarily needs every cover. What matters is that the home insurance matches how your property is actually used and the risks that come with it.
A fire is an experience no property owner wants. For me, however, it showed very concretely how important it is to think through, before an accident, what my home insurance actually protects.
An even more important lesson was that, as a property owner, you should not only look at whether the house or apartment is insured. For a rented property, liability insurance, loss of rental income cover and other additional covers can also matter, helping manage risks in a situation where the property can no longer be used as normal. Home insurance feels like a cost until you need it. When something really happens, correctly chosen cover can turn out to be one of the most important decisions a property owner has made.
If you have a rented apartment or house, or plan to rent out property, it is worth thinking through the whole rental process in addition to insurance. If you want to know what your property’s rent could be today or need help finding a suitable tenant, get in touch – I will help organise the rental of your property as thoughtfully as possible.
Insurance terms and the scope of cover depend on the specific insurance contract. The experience described in this article concerns my particular case, and before taking out insurance you should always review your own offer and the applicable terms.
Many people’s plans to buy a home stall on one question: where to get the 20% down payment? Six options many buyers do not know about.

As a property owner or landlord we usually think about yield and low costs. My house in Pärnu burned down, and only then did I understand home insurance.
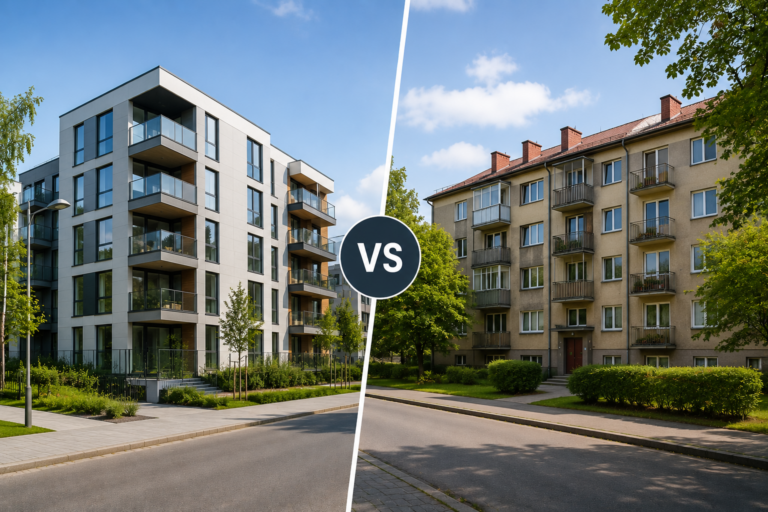
When buying an apartment, many people quickly reach one question: a new development or the secondary market? Which is the better choice today?
Once a month I send you a thorough market overview and interesting real estate finds.